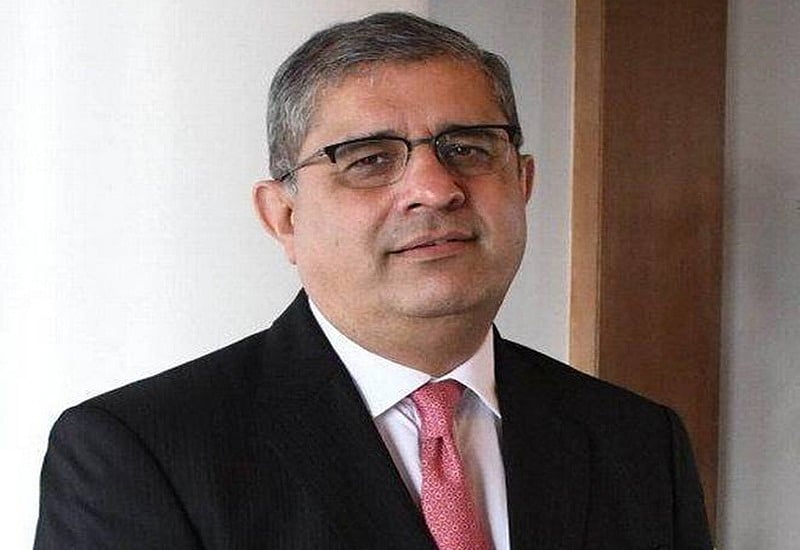
India's banking sector faces growing pressure from tighter liquidity, rising deposit costs and expectations of higher interest rates, even as demand for loans remains strong, Axis Bank Managing Director and Chief Executive Officer Amitabh Chaudhry said on Monday.
Speaking at a media summit, Chaudhry highlighted the challenges banks face in balancing profitability, lending growth and risk management.
He said liquidity was initially expected to remain comfortable for two quarters following inflows of approximately $14.3 billion through the foreign currency non-resident (FCNR) deposit scheme.
However, the Reserve Bank of India (RBI) subsequently absorbed part of the surplus, contributing to higher incremental deposit rates.
Rising Interest Rates Could Slow Bank Credit Growth
Chaudhry warned that inflationary pressures, geopolitical uncertainty surrounding the West Asia conflict and expectations of interest rate increases could raise banks' funding costs.
Higher borrowing expenses could also affect loan demand and borrowers' repayment capacity.
He expects credit growth to moderate during the second half as favourable base effects from the first half diminish.
Nevertheless, several factors could support lending activity.
Longer working capital cycles, increased inventory requirements and higher procurement costs are creating additional financing needs for businesses.
Infrastructure spending, project finance demand and banking expansion into underserved markets could provide further opportunities.
Non-banking financial companies (NBFCs), improved borrower data and stronger credit assessment capabilities could also support lending.
Chaudhry emphasised that prudent risk management would remain essential as financial conditions tighten.
Despite emerging challenges, Chaudhry believes Indian banks are better equipped to withstand asset quality pressures than during the previous rapid credit expansion cycle.
He attributed this resilience to stronger capital positions, improved underwriting standards and higher provisioning levels.
According to Chaudhry, capital buffers are approximately 500 basis points higher than during the earlier cycle.
Provision coverage ratios have also improved substantially, rising from around 40-45% to 70-75% at most banks.