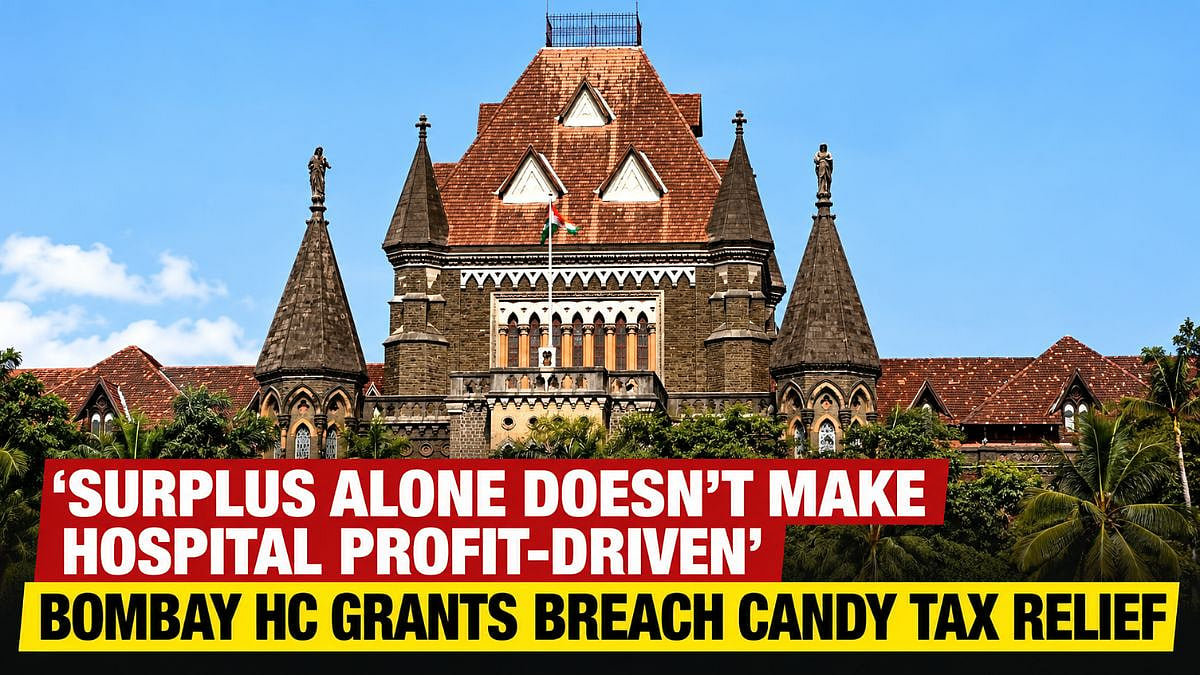
Mumbai, October 13, 2026: In a relief for Breach Candy Hospital Trust, the Bombay High Court has directed the Income Tax Department to grant tax exemption approval to the trust for assessment years spanning 2002-03 to 2021-22. The court held that the hospital’s surplus income alone cannot be treated as proof that it operates for profit.
High Court Quashes Tax Orders
A bench of Justices BP Colabawalla and Farhan Dubash allowed two petitions filed by the hospital trust, quashing orders passed by the Chief Commissioner of Income Tax in 2010 and 2012 that had rejected its applications for approval under Section 10(23C)(via) of the Income Tax Act.
The provision covers hospitals existing solely for philanthropic purposes and not for profit. The court directed the competent tax authority to grant the approvals within eight weeks.
Surplus Income Not Proof Of Profit Motive
“The relevant inquiry is to see the use of those receipts including acquiring assets for aiding better medical relief,” the bench observed, emphasising that the hospital’s income had to be assessed in the context of how it was used.
The tax authorities had questioned the hospital’s surplus income and raised concerns over matters including concessions and free treatment for poor patients, doctors’ consultation rooms and the collection of professional fees.
Rejecting the argument that surplus income by itself indicated a profit motive, the court said it “does not, by itself, establish that the Hospital existed for profit.”
Hospital Expenditure Taken Into Account
The bench noted that the hospital’s constitutional documents prohibited the distribution of profits and that its income was used for hospital operations and facilities. It also found no evidence of fictitious or diverted expenditure, or of funds being appropriated for private purposes unrelated to the hospital’s objectives.
The court further considered the hospital’s spending on depreciation and capital expenditure for equipment and facilities, observing that such expenditure had to be taken into account while examining its activities.
Also Watch:
Approvals Cover Two Assessment Periods
The two approvals cover assessment years 2002-03 to 2010-11 and 2011-12 to 2021-22, respectively. The court clarified that the directions applied to these specified periods.
To get details on exclusive and budget-friendly property deals in Mumbai & surrounding regions, do visit: https://budgetproperties.in/