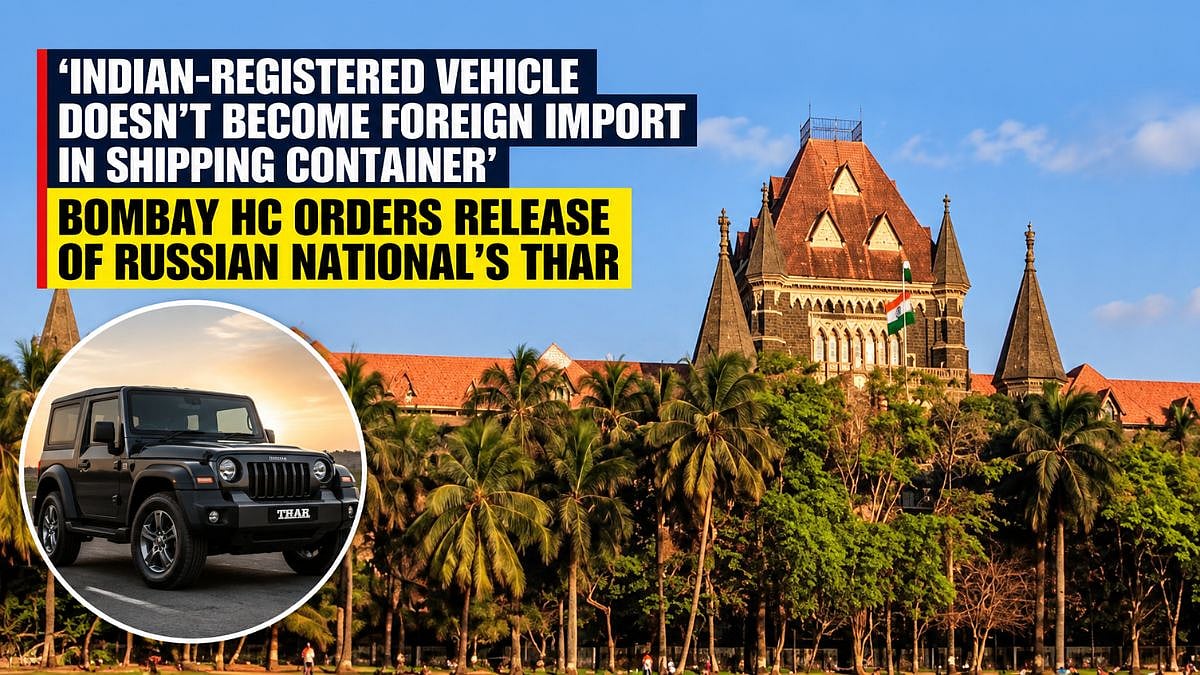
Mumbai, October 2, 2026: An Indian-registered vehicle does not become a fresh foreign import merely because it is brought back to India in a shipping container after an overseas road trip, the Bombay High Court has held while ordering the release of a Mahindra Thar belonging to Russian national Denis Vanin.
A bench of Justices M.S. Karnik and Sandesh Patil said the vehicle had legally left India as a private conveyance and its transportation in a maritime container for safety did not change its character.
“The vehicle in question is an Indian-registered asset and not a fresh foreign import,” the court said. It added that placing it in a cargo container “does not transform a domestic personal vehicle into an item of international trade cargo”.
Vehicle’s Overseas Journey
Vanin purchased the Thar in Goa on August 12, 2022, for personal use after paying applicable GST and road taxes. On July 5, 2024, he drove it out of India through the Sanauli land border into Nepal. He then travelled through China, Kazakhstan, Russia, Georgia, Armenia and Iran.
From Bandar Abbas, the vehicle was placed in a protective shipping container for its return by sea. It was loaded onto a vessel on November 13, 2024, and reached Nhava Sheva on November 17.
Customs Bill Of Entry Issue
Customs authorities required Vanin to file a Bill of Entry before releasing the vehicle. He said he was willing to comply but could not file it electronically because ICEGATE required an Import-Export Code (IEC) and/or GSTIN. He did not have a GSTIN as the vehicle was for personal use.
The court examined how the Thar had originally left India. Customs had allowed Vanin to cross the Sanauli border with the vehicle as a private conveyance carrying passenger luggage.
Court Examines Customs Rules
Referring to Section 43(1) of the Customs Act, the bench noted that private conveyances carrying only passenger luggage are exempt from cargo reports and departure clearances. There was nothing on record showing that Vanin had been required to complete additional formalities when the vehicle left India.
The bench also noted that Section 51, which applies to commercial goods, falls under Chapter VII, while Vanin’s vehicle had left India as a private conveyance under Chapter VI.
Court Allows Manual Filing
On the difficulty in filing the Bill of Entry electronically, the court observed, “Expecting the petitioner to perform a condition which is an impossibility is violative of the established principle that the law does not compel the performance of an impossibility.”
The court permitted Vanin to file the Bill of Entry without an IEC and/or GSTIN. If electronic filing was not possible, Customs was directed to accept the documents physically and allow a manual Bill of Entry.
Also Watch:
The Thar was ordered to be released on furnishing the required bond. Customs could verify whether Vanin had claimed export benefits or incentives, while Vanin would have to cooperate with any subsequent adjudication.
To get details on exclusive and budget-friendly property deals in Mumbai & surrounding regions, do visit: https://budgetproperties.in/