The four-month southwest monsoon season (June to September 2026) in India has entered its withdrawal phase. In June, the monsoon arrived four days late and subsequently stalled for almost three weeks. Early July rains revived hopes, but precipitation in August and September was less than satisfactory.
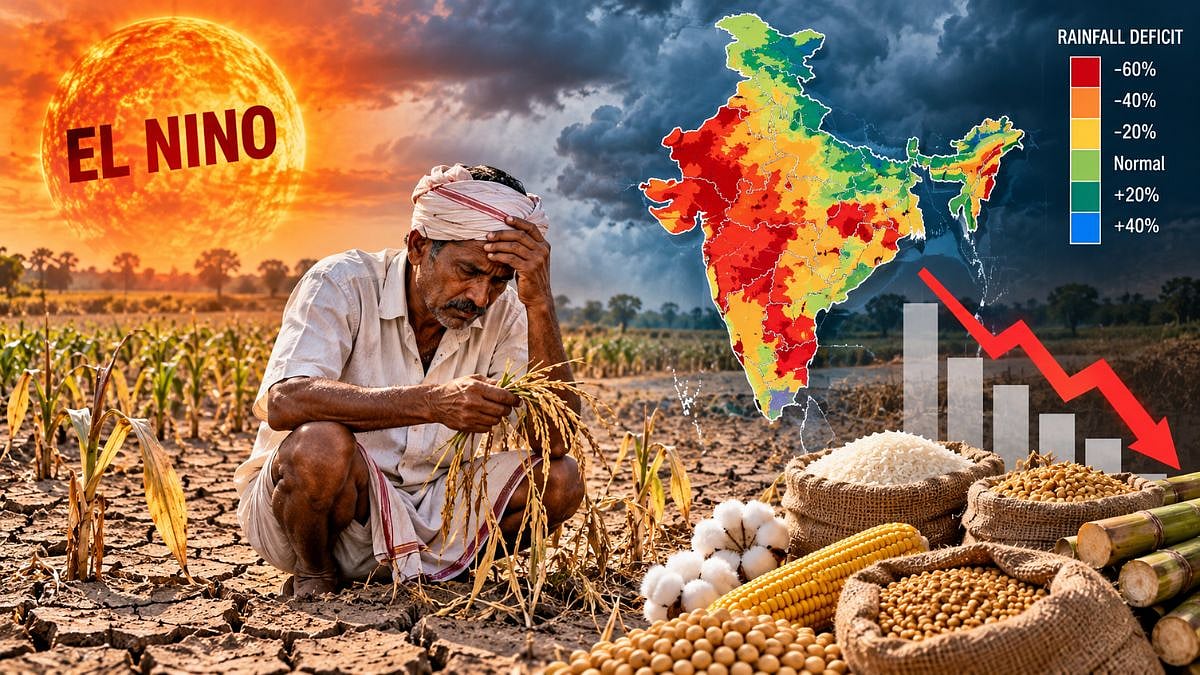
As a result, by the end of September, the country faced a rainfall deficit of 15%. The temporal and spatial distribution of rainfall has been uneven. Of the country’s 36 meteorological subdivisions, 19, representing 51% of the national area, recorded deficient rainfall. Even among the remaining subdivisions classified as having received ‘normal’ rainfall, some were borderline cases.
Major Agricultural Regions Face Moisture Stress
The cumulative rainfall map shows key growing areas, including Punjab, Haryana, parts of Rajasthan, parts of Gujarat (Saurashtra and Kutch), parts of Maharashtra (Marathwada), almost the whole of Andhra Pradesh, Telangana and Karnataka, as well as Assam and the Northeast, facing varying degrees of moisture stress.
The damage caused by El Niño-induced dry conditions is clearly visible. The situation has worsened due to the high cost and limited availability of fertilisers following military action in the Persian Gulf region.
The accompanying table shows the acreage under Kharif crops in 2025 and 2026, the production target for 2026, the forecast production for 2026 and the government’s estimated production for Kharif 2025.
The production forecast for the current Kharif season is based on this author’s proprietary research.
Kharif Production Expected To Fall Short
In most cases, the planted area is lower than during the previous Kharif season. The poor distribution of rainfall has affected the planted area, yields and production. Rice, pulses, cotton, soybean, groundnut and sugarcane crops have been affected.
The Kharif 2026-27 harvest is expected to fall short of the season’s production target and below the government’s estimate for the previous year. In some regions, crop quality may also be affected.
The government usually releases its first advance estimate by the end of September. However, this season, the estimate had not been published even by October 12.
Imports And Inflation Risks Increase
A smaller harvest would further tighten the supply-demand fundamentals of several crops. Rice buffer stocks of 40 million tonnes offer some comfort. At the same time, imports of several commodities are set to increase: pulses to about 7.5 million tonnes, vegetable oils to 16-17 million tonnes and cotton to more than 7 million bales.
High international energy costs and a weak rupee could exacerbate the price situation and heighten inflation expectations. The government may tighten restrictions on agricultural trade.
El Niño Poses Fresh Threat To Rabi Crops
The outlook raises a bigger concern. According to meteorological reports, El Niño may intensify further during October-November-December. This coincides with the completion of the Kharif harvest and the planting of Rabi crops, mainly wheat, rice, maize, oilseeds such as rapeseed, mustard and groundnut, and pulses such as chickpea and lentil.
Adequate winter rainfall is critical for Rabi crops.
Indian wheat is already close to its heat-tolerance limit. Warmer days in January and February, followed by heatwaves in March, could reduce the harvest. Fodder availability for livestock will also be a challenge. Reservoir storage levels are less than satisfactory and could reach critical levels in the first quarter of 2027.
Policy Options Before The Centre
What policy options are available to the government? Basic customs duty on palm, soybean and sunflower oils has already been reduced, but imports of refined oils could receive further support through additional duty reductions.
For pulses, a liberal import policy remains in place until March 2027 and could be extended. Some restrictions on diverting rice, maize and sugarcane for ethanol production cannot be ruled out.
G. Chandrashekhar is a senior journalist and policy commentator specialising in commodity markets. Views are personal.