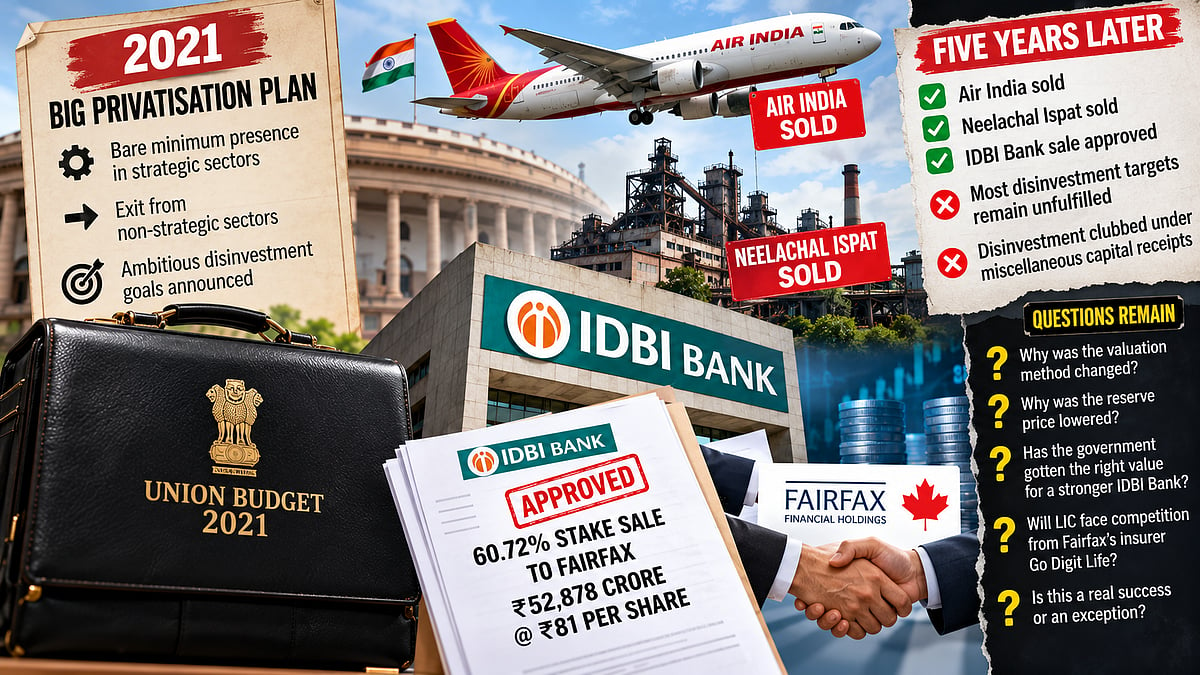
Five years ago, the union budget announced its most ambitious privatisation programme to date. The government would keep a bare minimum presence in four strategic sectors and exit everything else. Five years later, the privatisation has resulted in the sale of Air India and Neelachal Ispat, and this week's approval of the sale of IDBI Bank.
While the government will present it as proof of its privatisation drive, it should be read as an exception rather than a success. As they say, proof of the pudding lies in the eating; the country has largely failed to carry out its disinvestment policy. Instead, the entities remain the same while the government continues to collect dividends and lease the assets: a self-serving model that doesn't match the government's lofty 2021 announcements.
What's more, the government has adjusted its books to tailor itself to the current position. Disinvestment doesn't even have its own line in the budget. It is part of “miscellaneous capital receipts” alongside asset monetisation.
Turning to the sale of the IDBI Bank itself to Canada-based Fairfax Financial Holdings, which came after five years, two rounds of bidding, and the rejection of bids that fell short of the reserve price, many questions remain unanswered. The deal is also not yet done: the Reserve Bank of India must still clear Fairfax as fit and proper.
While the Cabinet Committee on Economic Affairs approved the sale of a 60.72 per cent stake to a Fairfax Financial Holdings-linked entity for ₹52,878 crore, at ₹81 a share, this was below the initial reserve price of ₹94.42. However, the government used two valuation agencies that arrived at a benchmark price of ₹75.99 per share, below Fairfax's ₹81 per share, which the government cites in its defence. What we need to know is why it changed its valuation method between the two rounds, and why the change lowered the bar for the buyer.
What is also open to criticism is that over the past five years, the bank has improved its financial health considerably. Its net profit for 2025-26 was ₹9,513 crore, compared with around ₹1,359 crore in 2020-21, a year before it was put up for sale. So, the reserve price should have actually been higher than even the initial one.
Another thing to consider is that post-sale, the LIC will continue to hold a stake in the bank. So, could LIC possibly face competition from Go Digit Life, Fairfax's own insurer, which Fairfax plans to fold into IDBI through the same banking channel it has relied on?
These issues tell us that while the government can push ahead with disinvestment when it wants to, delays can undo whatever it set out to achieve.