What To Check Before Pre-Closing A Credit Card EMI
Credit card EMI pre-closure can help you repay outstanding dues before the scheduled tenure ends. Before closing an EMI, check the outstanding principal, foreclosure charges, interest, processing fees, GST, cashback reversals and credit limit restoration to avoid unexpected costs.
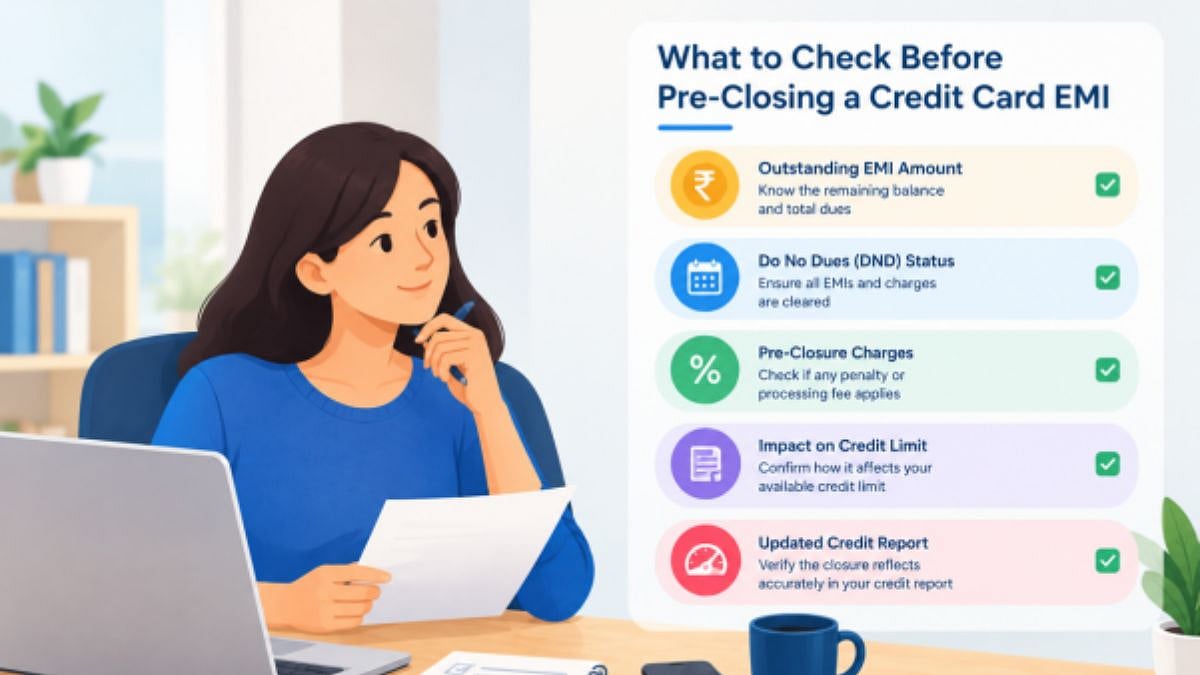
What To Check Before Pre-Closing A Credit Card EMI | File photo
Large purchases can be difficult to manage, especially with a tight monthly budget. A credit card EMI can spread the cost over monthly payments. Before you apply credit cards for large purchases, understand the EMI terms, charges and pre-closure conditions. At times, you may receive financial windfalls and decide to repay the EMI before the scheduled tenure ends. Before doing so, check whether any additional costs apply. This guide covers the main things to check before pre-closing a credit card EMI.
What Is Credit Card EMI Pre-Closure?
Credit card EMI pre-closure is settling the remaining EMI balance before the original repayment date. You close the EMI early and provide the settlement amount instead of paying the remaining instalments as scheduled.
Do note that the pre-closure amount can differ from the total of your remaining instalments. The interest would be adjusted that would otherwise have been charged on the remaining tenure, while pre-closure fees or other applicable charges still apply. You may also need to submit a formal request to close the EMI, depending on the issuer.
What Should You Check Before Pre-Closing a Credit Card EMI?
You should check the exact amount due, applicable charges and the issuer’s pre-closure terms before pre-closing an EMI. Understanding them can help you avoid unexpected costs and ensure the EMI is closed correctly.
These conditions vary from issuer to issuer. Here are the main things to check before pre-closing a credit card EMI:
Outstanding Principal AmountOutstanding Principal Amount
This is the portion of the EMI balance that is still due. Check the outstanding principal amount before starting the pre-closure process. Don't calculate the closure amount by adding all the remaining EMIs together.
The remaining instalments include future interest and are treated differently when closing the EMI. You can ask the card issuer for the current outstanding amount and the exact amount needed for pre-closure.
Foreclosure Charges
Check whether foreclosure charges apply to the EMI. The card issuer sets these charges, which may be calculated on the outstanding amount or based on a specified fee structure. Confirm the exact amount before making the payment so you can compare the cost of closing the EMI with the cost of continuing it.
Interest Payable Up to the Pre-Closure Date
Check the interest due up to the date you plan to close the EMI. The amount may differ from the interest included in the remaining EMIs. When you apply for credit cards, review the EMI terms and ask the issuer for the exact pre-closure amount, including any interest due up to the closure date.
Processing Fee and Applicable GST
Review the processing fee charged when the EMI was booked and check whether any part of it is refundable. Also check the applicable GST on charges and other amounts included in the pre-closure calculation.
The processing fee is generally a separate cost from the foreclosure charge. The exact treatment depends on the terms attached to the EMI.
Cashback or Other EMI Benefits
Cashback usually doesn't apply to credit card EMIs. Still, you can check whether your EMI includes cashback, an instant discount or reward points. Offers on credit cards may have specific terms for early EMI closure. Confirm whether any cashback or other benefit will be reversed, reduced or adjusted against the amount payable.
Total Pre-Closure Amount
Ask the card issuer for the total pre-closure amount. This should show the amount required to settle the EMI, along with applicable charges, taxes and other adjustments.
Then compare it with the cost of continuing the remaining EMIs. Closing the EMI early can reduce future interest, but the savings should be enough to justify the foreclosure charges and other costs.
Available Credit Limit After Pre-Closure
Check when your available credit limit will be restored equal to the amount tied up in the EMI. The limit may not increase immediately because the issuer process the pre-closure request and payment first.
Once the issuer confirms the closure, check your card account to make sure the available limit has been updated correctly.
Confirmation of EMI Closure
After completing the payment, obtain confirmation of EMI closure from the card issuer. Keep the payment details, service request number and closure communication for your records.
Also check your next credit card statement. The closed EMI should no longer appear as an active instalment and there should be no unexplained balance or additional charge related to the closed EMI.
Conclusion
Before pre-closing a credit card EMI, you should check all the charges, terms, and amounts payable. It is important to stay updated about the closure process, exact amount payable and available credit limit. After payment, keep the closure confirmation and check your next statement to ensure the EMI has been closed correctly. If you want to apply for credit cards, do check documents required for credit card applications to avoid delays and rejection.
RECENT STORIES
-
-
-
-
-