Taxation Should Treat The Non-Profit Sector As A Partner In Development
The Income Tax Act, 2025, introduced changes sought by the non-profit sector, including a unified framework and streamlined registration process. The article argues that further reforms are needed to balance accountability with financial sustainability, enabling non-profits to build endowments, undertake multi-year projects and attract greater philanthropic funding.
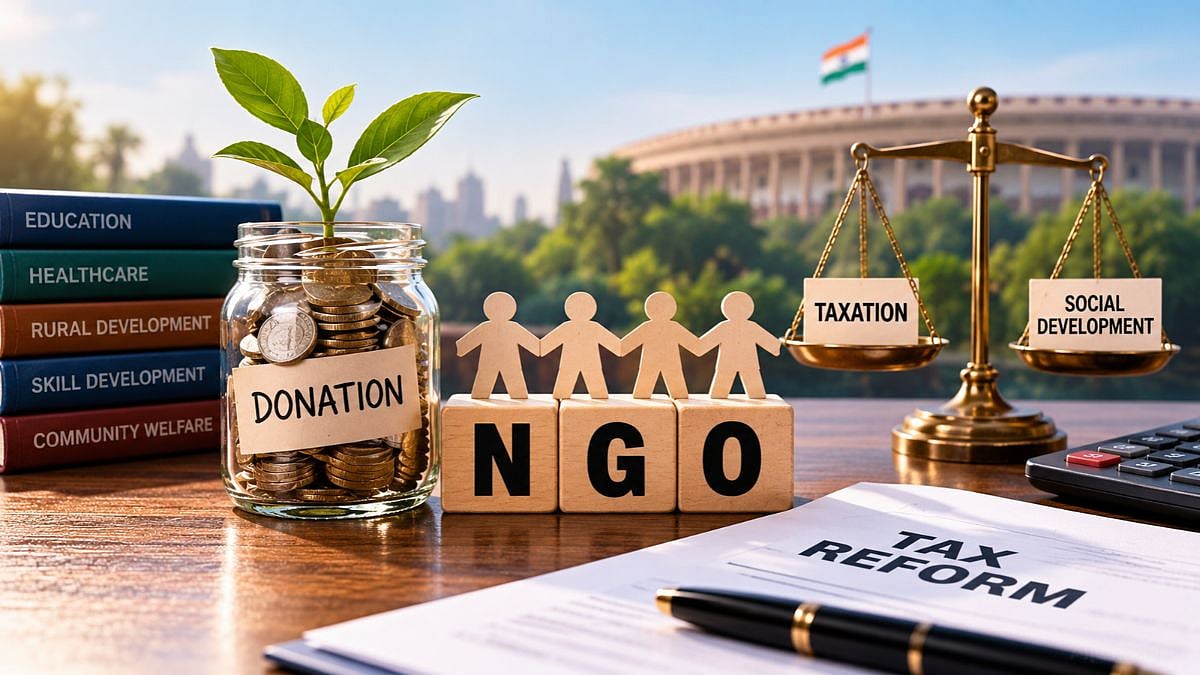
Policy reforms could help non-profits strengthen financial sustainability and expand their social impact | Representational Image
India’s growth story is often measured through economic expansion, infrastructure creation and technological advancement. Yet, many of its most meaningful social transformations have been driven by non-profit organisations (NPOs) that bridge the gap between policy and grassroots realities. Against this backdrop, understanding the tax regulatory framework governing non-profits becomes critical.
Encouragingly, the Income Tax Act, 2025, incorporated several reforms that the non-profit sector has sought for years and reflects a genuine effort to simplify a historically complex regime. For instance, trusts, societies and educational institutions have been brought under a unified framework, while the cumbersome three-tier structure of Sections 12A, 12AA and 12AB has been replaced by a single streamlined online registration process. Equally significant is the government’s willingness to refine the law in response to stakeholder feedback. Concerns over the proposed 30 per cent tax on all anonymous donations led the Select Committee to recommend restoring the exemption available to wholly religious institutions, a recommendation ultimately incorporated into the final Act.
The challenge now is to extend that same spirit to other provisions where the balance between accountability and sustainability remains unsettled.
As per estimates, India has roughly 33 lakh NGOs and community service organisations, while the NGO Darpan portal lists around 1.87 lakh. Yet only about 5 lakh NPOs are registered under the Income Tax framework, highlighting that the gap is not merely a story of paperwork or under-registration, but also partly reflects the incentives embedded within the tax regime itself. To understand why many organisations remain outside the formal tax net, one must first understand the bargain the government offers to those within it.
The Challenge Of The 85 Per Cent Rule
At its core, that bargain is simple — tax benefits in exchange for public service. The principal instrument for enforcing this principle is the 85 per cent rule, wherein, to retain tax-exempt status, an NPO must apply at least 85 per cent of its income towards its stated objectives within the same financial year. If it fails to do so, the shortfall may be taxed at the maximum rate as residual income.
The challenge arises when a rule designed to prevent hoarding begins to constrain legitimate long-term planning. Development work rarely conforms to annual accounting cycles. For example, a hospital expansion, a watershed programme, a tribal education initiative or a women’s livelihood project may require years of preparation before substantial expenditure takes place. The result is a framework that sometimes prioritises the timing of expenditure over the effectiveness of outcomes.
The same tension between control and flexibility surfaces elsewhere in the framework regarding the General Public Utility clause. Under the provision, an organisation classified under general public utility — for instance, one involved in collective marketing of handicrafts — risks losing its tax exemption if commercial receipts exceed 20 per cent of total income, even when such earnings are ploughed back into charitable activities.
Building Long-Term Financial Resilience
If these provisions reveal where the framework strains, they also point to how it might be eased. Reform that listens is reform worth building on, and it sets the tone for the calibration the framework still needs.
In this regard, the first priority should be to help non-profits build long-term financial resilience rather than depend perpetually on fresh donations. Under the current framework, the 15 per cent of income that may be accumulated must largely remain in prescribed low-yield instruments.
While this protects capital, it does little to preserve its real value in the face of inflation. Allowing a portion of accumulated funds to be invested, within prudent regulatory limits, in diversified growth-oriented instruments would enable charities to gradually build endowments and generate their own income streams.
As a second priority, India should move from rigid expenditure mandates to outcome-based accountability. Globally, the emphasis is less on annual spending targets and more on ensuring that charitable assets ultimately serve public purposes. While US private foundations are required to distribute only around 5 per cent of their investment assets annually, the UK relies on a broader public-benefit framework rather than fixed spending thresholds.
India could similarly allow registered NPOs to carry forward a larger share of income for multi-year projects and endowment-building, subject to transparent disclosures, audited utilisation plans and periodic reporting on outcomes.
Revisiting Commercial Income Thresholds
The third priority is to strengthen the financial sustainability of non-profits by encouraging both mission-linked revenue generation and philanthropy. Not all income earned by an NPO is evidence of commercialisation. The Supreme Court, in ACIT vs. Ahmedabad Urban Development Authority (2022), recognised this distinction through its “cost-plus” test, holding that activities charging at or marginally above cost are fundamentally different from profit-oriented commercial enterprises.
Embedding this principle into the administration of the 20 per cent commercial-income threshold would help ensure that organisations are assessed by the nature and purpose of their activities rather than by a rigid numerical limit alone.
Encouraging Charitable Giving
As the fourth priority, India must do more to encourage charitable giving itself. A case in point is the UK’s Gift Aid programme, which allows registered charities to reclaim an additional 25 per cent from the government for every pound donated by a taxpayer, significantly increasing the value of private contributions.
A similar incentive mechanism — whether through enhanced tax deductions, matched contributions for priority sectors or a Gift Aid-style top-up — could help expand philanthropic capital and reduce dependence on grants.
Taken together, a thriving non-profit sector is a partner in development, not a drain on the exchequer. A tax framework that nudges these organisations from anxious compliance towards genuine sustainability would ultimately reward both the government that designs it and the citizens it is meant to reach.
Rakshita Malviya is a Public Policy Consultant in the office of a Member of Parliament (Lok Sabha).
To get details on exclusive and budget-friendly property deals in Mumbai & surrounding regions, do visit: https://budgetproperties.in/
Published on: Thursday, October 29, 2026, 10:16 PM ISTRECENT STORIES
-
-
-
-
-