Maharashtra Consumer Commission Orders United India Insurance To Pay ₹87.33 Lakh To Solapur Textile Factory Owner Over Rejected Fire Damage Claim
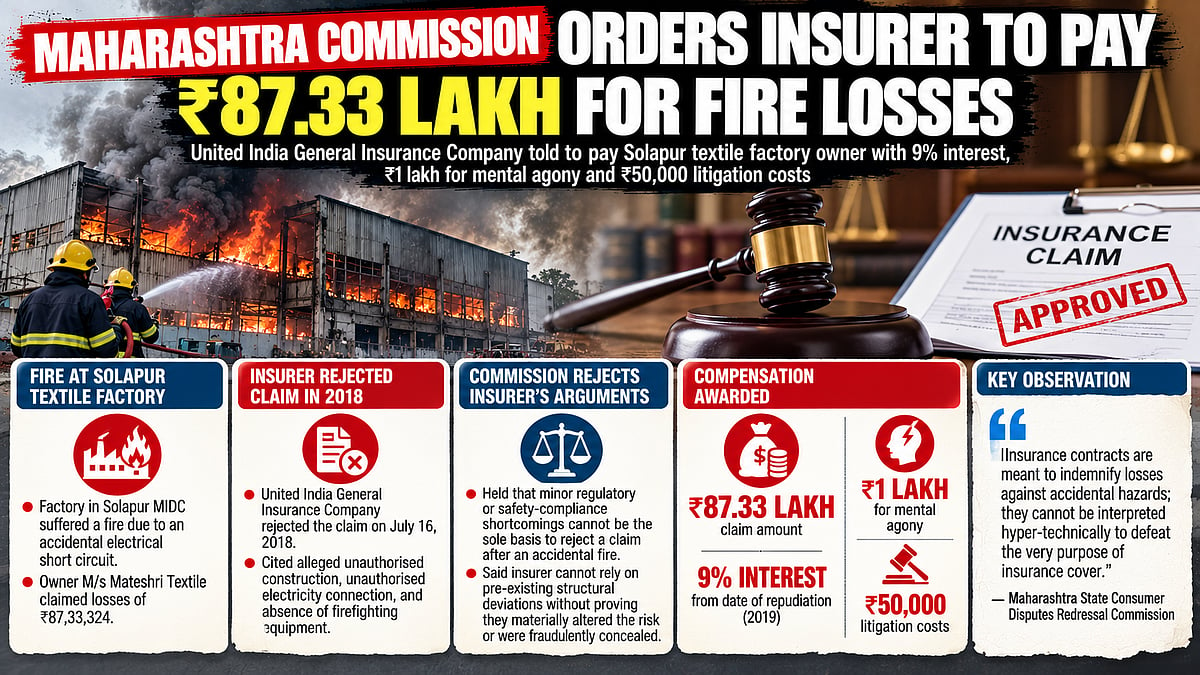
The Maharashtra State Consumer Disputes Redressal Commission has directed United India Insurance to pay ₹87.33 lakh to Solapur-based Mateshri Textile over a rejected fire damage claim. The commission held that minor safety or regulatory lapses could not automatically justify repudiation. It also awarded 9 per cent interest, ₹1 lakh for mental agony and ₹50,000 in litigation costs.
Maharashtra Consumer Commission Orders United India Insurance To Pay ₹87.33 Lakh To Solapur Textile Factory Owner Over Rejected Fire Damage Claim | AI
Mumbai: The Maharashtra State Consumer Disputes Redressal Commission has directed a United India General Insurance Company, to pay ₹87.33 lakh to a Solapur MIDC based textile factory owner for losses caused by a fire, holding that the insurer’s rejection of the claim on grounds including unauthorised construction, an unauthorised electricity connection and the absence of firefighting equipment was unjustified.
Nine Per Cent Interest Ordered
The policy was purchased under the extraneous peril covered under standard fire policies. The commission in its orders has maintained that the said compensation amount has to be paid along with 9 percent interest rate from the date of repudiation, 2019. The Commission in its verdict maintained that apart from the fire losses, the insurance policy is liable to pay Rs 1 lakh towards the mental agony caused to the company owner along with Rs 50,000 towards the litigation charges.
Absence Of Firefighting Equipment Cited
“The insurance firm (opponent) has taken a technical plea that the absence of fire-fighting equipment constitutes a breach of general condition clause 3 of the policy. We find this ground untenable. In commercial and industrial establishments, minor regulatory or safety compliance shortcomings unless expressly warranted as a condition precedent to the contract's attachment in unequivocal terms cannot form the sole basis to reject a claim arising from an accidental fire caused by an electrical short circuit. Insurance contracts are meant to indemnify losses against accidental hazards; they cannot be interpreted hyper-technically to defeat the very purpose of insurance cover,”the order copy reads.
In its order, the commission observed that an insurer that inspects premises, issues policies and accepts premiums cannot subsequently rely on pre-existing structural deviations to reject a claim without establishing that the deviations materially altered the insured risk or were fraudulently concealed and connected to the loss.
Assets Insured For ₹91.50 Lakh
The complainant M/s Mateshri Textile, had obtained three insurance policies covering his Solapur based factory building, plant and machinery, stock and raw materials, with a total sum insured of ₹91.50 lakh. The policies were intended to protect the business assets against accidental risks, including fire.
According to the commission’s order, the factory suffered a fire caused by an accidental electrical short circuit. The complainant assessed the loss at ₹87,33,324 and submitted supporting documents, including primary records, a police panchnama, fire brigade reports and intimation to the insurer’s surveyor.
ALSO READ
However, the insurance company rejected the claim through a letter dated July 16, 2018, citing alleged violations relating to construction, the electricity connection and the absence of firefighting appliances. The insurer also questioned whether the complainant had produced sufficient expert accounting evidence to establish the exact quantity of stock lost.
Rejecting the insurer’s arguments, the commission held that minor regulatory or safety-compliance shortcomings cannot, by themselves, justify rejecting a claim arising from an accidental fire unless the relevant requirement has been expressly stipulated as a condition precedent to the insurance cover.
Holding that the insurer’s decision amounted to deficiency in service and an unfair trade practice, the commission partly allowed the complaint and directed the company to pay the assessed claim amount, interest and the additional compensation and litigation costs.
To get details on exclusive and budget-friendly property deals in Mumbai & surrounding regions, do visit: https://budgetproperties.in/
RECENT STORIES
-
-
-
-
-